Meet Our EGAs: Greg Lingerfelt—Florida Adjuster & Appraiser
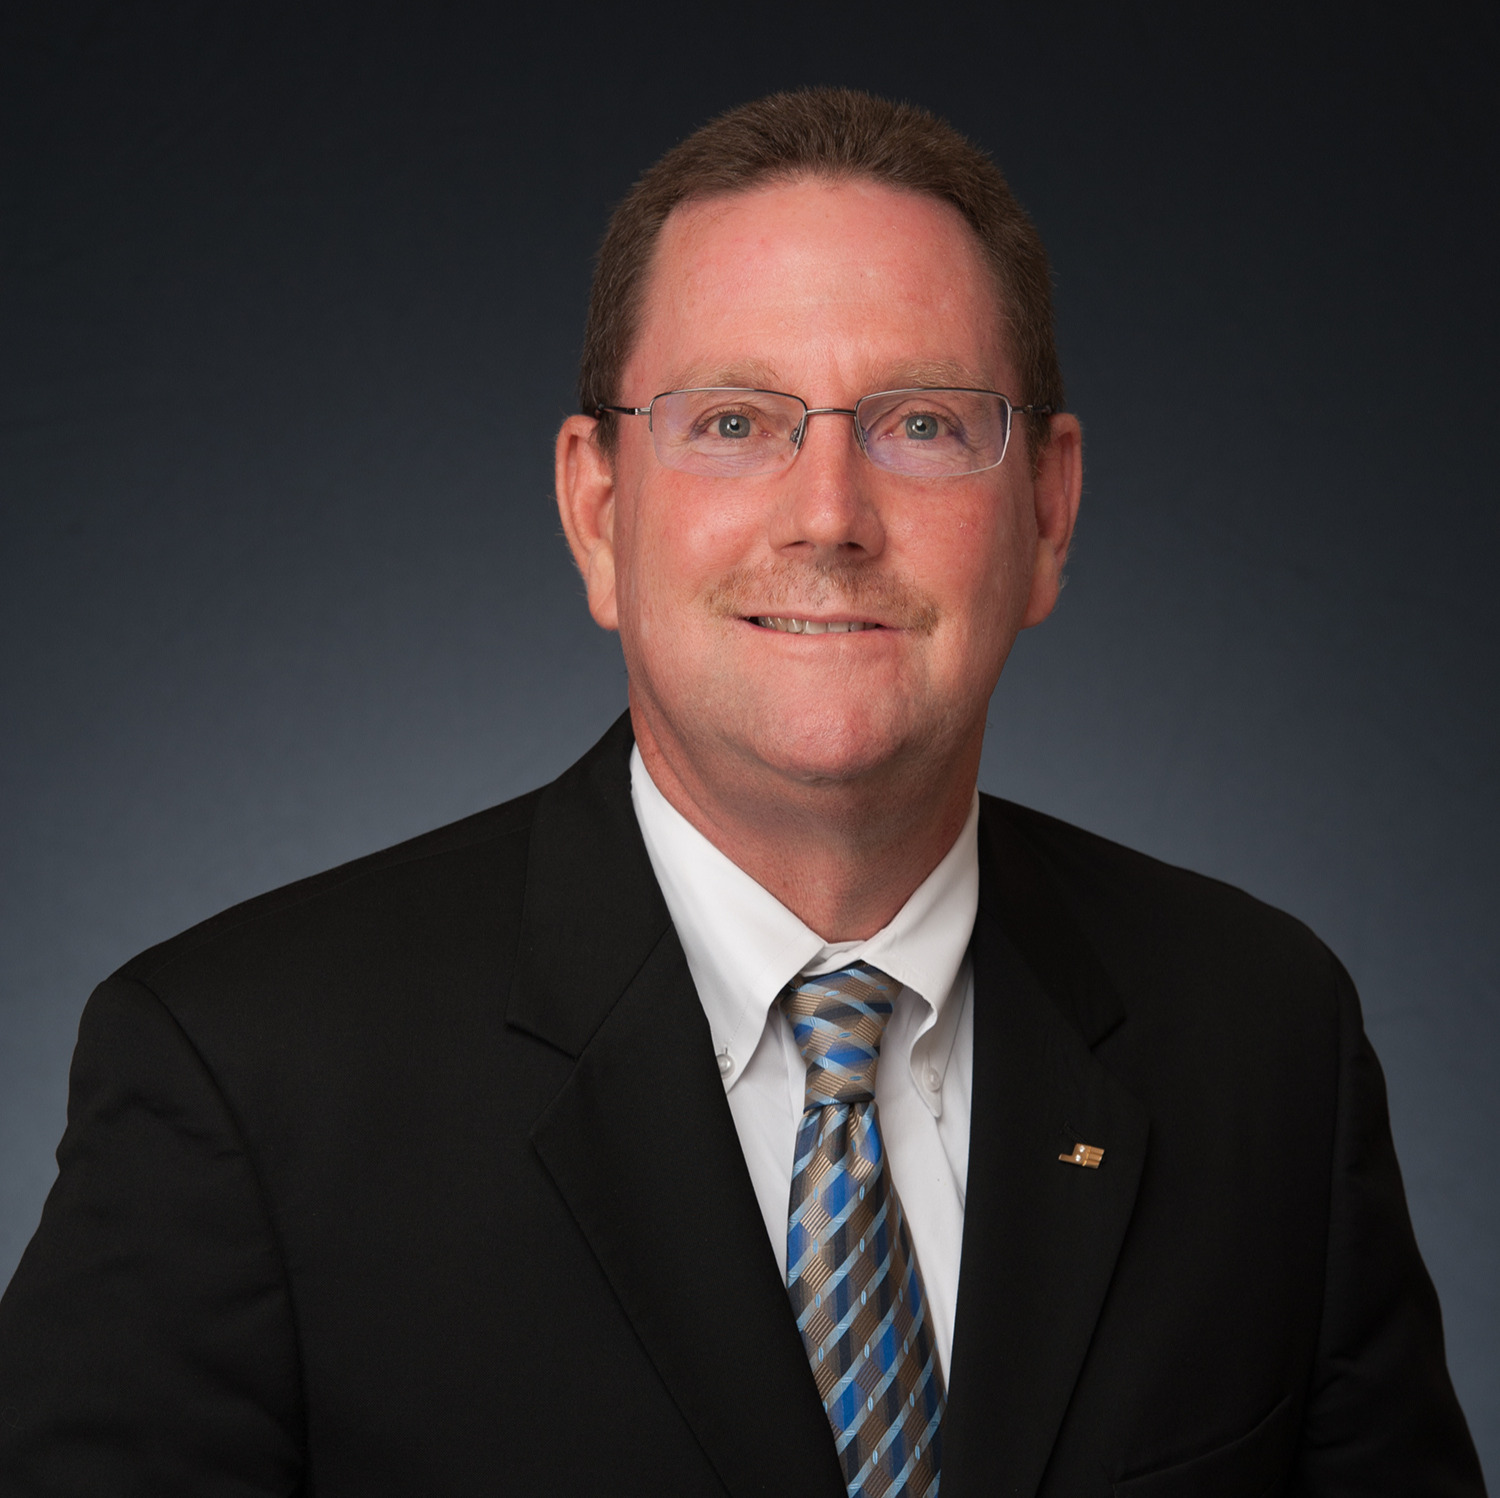
Greg Lingerfelt, AIC, CIA, CIU – EGA
September 23rd 2026
 Davies’ Executive General Adjusters are elite among Large Loss & Specialty claims adjusters in the U.S., handling the most complex and costly claims nationally and internationally. In this series, learn more about who they are, what they do, industry trends they’re seeing, and the most interesting project each has worked on to date.
Quick Background
Since 1988, Greg has specialized in residential and commercial property losses, including business interruption, jewelers block and employee dishonesty claims. He has handled major hurricane-related losses and served as an appraiser, umpire and arbitrator on multimillion dollar disputes. Recognized as a premier appraiser in Florida, Greg plays a key role in training property adjusters.
Home: West Palm Beach, FL
Region: Florida
Certifications: NFIP-Certified
In this Q&A, Greg, a leading Florida appraiser, shares his insights into litigation trends, assignment of benefits and complex claims handling.
Q&A
As a premier appraiser in Florida, how has the surge in litigation and assignment of benefits issues changed your approach to field inspections?
The increase in litigation has definitely changed the way I handle day-to-day claims inspections.
Years ago, my focus was primarily on areas the insured identified as damaged. Today, I take a much broader approach. In addition to documenting the claimed damage, I will often inspect and photograph areas that are undamaged and/or damages unrelated to the reported loss. This additional documentation can become extremely important if a claim later ends up in litigation, and additional damages are alleged. It helps ensure the insurer has a clear record of the property’s condition and can support its position on the damages.
The rise in litigation has also made expert involvement more important. It’s not uncommon for me to bring in an engineer to assist in determining the cause of damage, whether it’s related to a covered event (i.e. wind) or the result of excluded perils (i.e. wear and tear, maintenance issues, and/or improper installation). I may also consult contractors to validate repair costs. If a claim proceeds to court, having experts involved from the beginning can be invaluable because they can testify and provide additional support for the insurer’s position.
From an appraisal standpoint, my inspection process hasn’t really changed. Before I visit a property, I carefully review both the insurer’s and the insured’s estimates to understand where the disagreements lie. During the inspection, I independently evaluate the damage and prepare my own estimate based on what I observe in the field.
I do believe the increase in litigation has led to more appraisal assignments. In many cases, when litigation is filed against an insurer that has an appraisal provision in its policy, defense counsel will move to compel appraisal. That typically pauses the litigation process and shifts the dispute into appraisal for resolution on damages. As a result, a large portion of my appraisal work now comes through defense attorneys who have taken over the handling of claims after litigation has been filed.
Assignment of Benefits (AOBs) have also changed significantly in Florida. Before the law changed, Appraisal Panels generally did not address invoices tied to an AOB because this portion of the claim remained with the contractor. Today, these invoices are often part of the damage being evaluated during appraisal. As a result, my inspections now frequently include assessing and pricing emergency mitigation work in addition to the rebuild cost. While it has added to the workload, it’s become an important part of ensuring the entire claim is properly assessed and resolved.
What do you think carriers underestimate most when it comes to the time and expertise required for complex commercial inspections?
I think some insurers recognize that handling a minor homeowner’s claim is very different from managing a large, complex commercial loss. They understand the value of bringing in a general adjuster or EGA from the start and will specifically request that level of expertise to manage the claim. Others, however, focus primarily on controlling upfront costs and simply want someone to inspect the loss, prepare an estimate, and wait until an appraisal demand or lawsuit arrives.
What many of these insurers don’t realize is that investing in experienced, qualified adjusters at the beginning of the process can significantly reduce the overall cost of a claim. The right adjuster does much more than document damage. They help identify issues early, resolve disputes before they escalate, and position the claim for a more efficient and cost-effective resolution.
When handling a large commercial loss, an experienced general adjuster or EGA takes a comprehensive approach from day one. It starts with a thorough review of the insurance policy to fully understand the available coverage, as well as any exclusions, limitations, or endorsements that may impact the claim. This early analysis helps establish a clear path forward and avoids surprises later in the adjustment process.
An experienced adjuster will also evaluate whether outside experts are needed to properly investigate and document the loss. Depending on the circumstances, this could include an origin and cause investigator for a fire claim, an engineer to assess structural or mechanical damage, or a forensic accountant to analyze business interruption losses. Bringing the right experts into the process early on often leads to better-informed decisions and more accurate claim evaluations.
The inspection process itself is equally important. A seasoned adjuster will conduct a detailed inspection of the property, documenting damages, and photographing all affected areas.
Whenever possible, inspections should be coordinated with retained experts. These joint inspections often provide valuable insight into causation, scope, and repair considerations, while also helping establish accurate reserves early in the process. As a result, insurers can avoid the problem of repeatedly increasing reserves as new information emerges.
Communication is another critical component of effective claim management. Experienced adjusters provide prompt initial reports and regular updates throughout the life of the claim, keeping carriers informed on investigative findings, claim progress, and reserve recommendations.
Most importantly, skilled adjusters actively work to resolve disagreements versus taking a reactionary position. When differences arise between the insurer assessment and the positions taken by the insured/ public adjuster/insured vendor, a knowledgeable GA or EGA will engage in discussions to find common ground. Too often, less experienced adjusters simply submit their estimate and move on, leaving disputes unresolved. Those unresolved issues frequently lead to costly appraisals or litigation that could have been avoided simply through communication between the parties.
Experienced adjusters are always mindful of potential subrogation opportunities. They evaluate possible third-party liability early in the claim, take steps to preserve critical evidence, and assist insurers in pursuing recovery from responsible parties when appropriate. By identifying these opportunities early on, insurers can improve their chances of recovery.
Get in touch with Greg to learn more about his service regions and capabilities, and learn more about our overall Specialty Risk Division solutions.
-
June 24th 2026
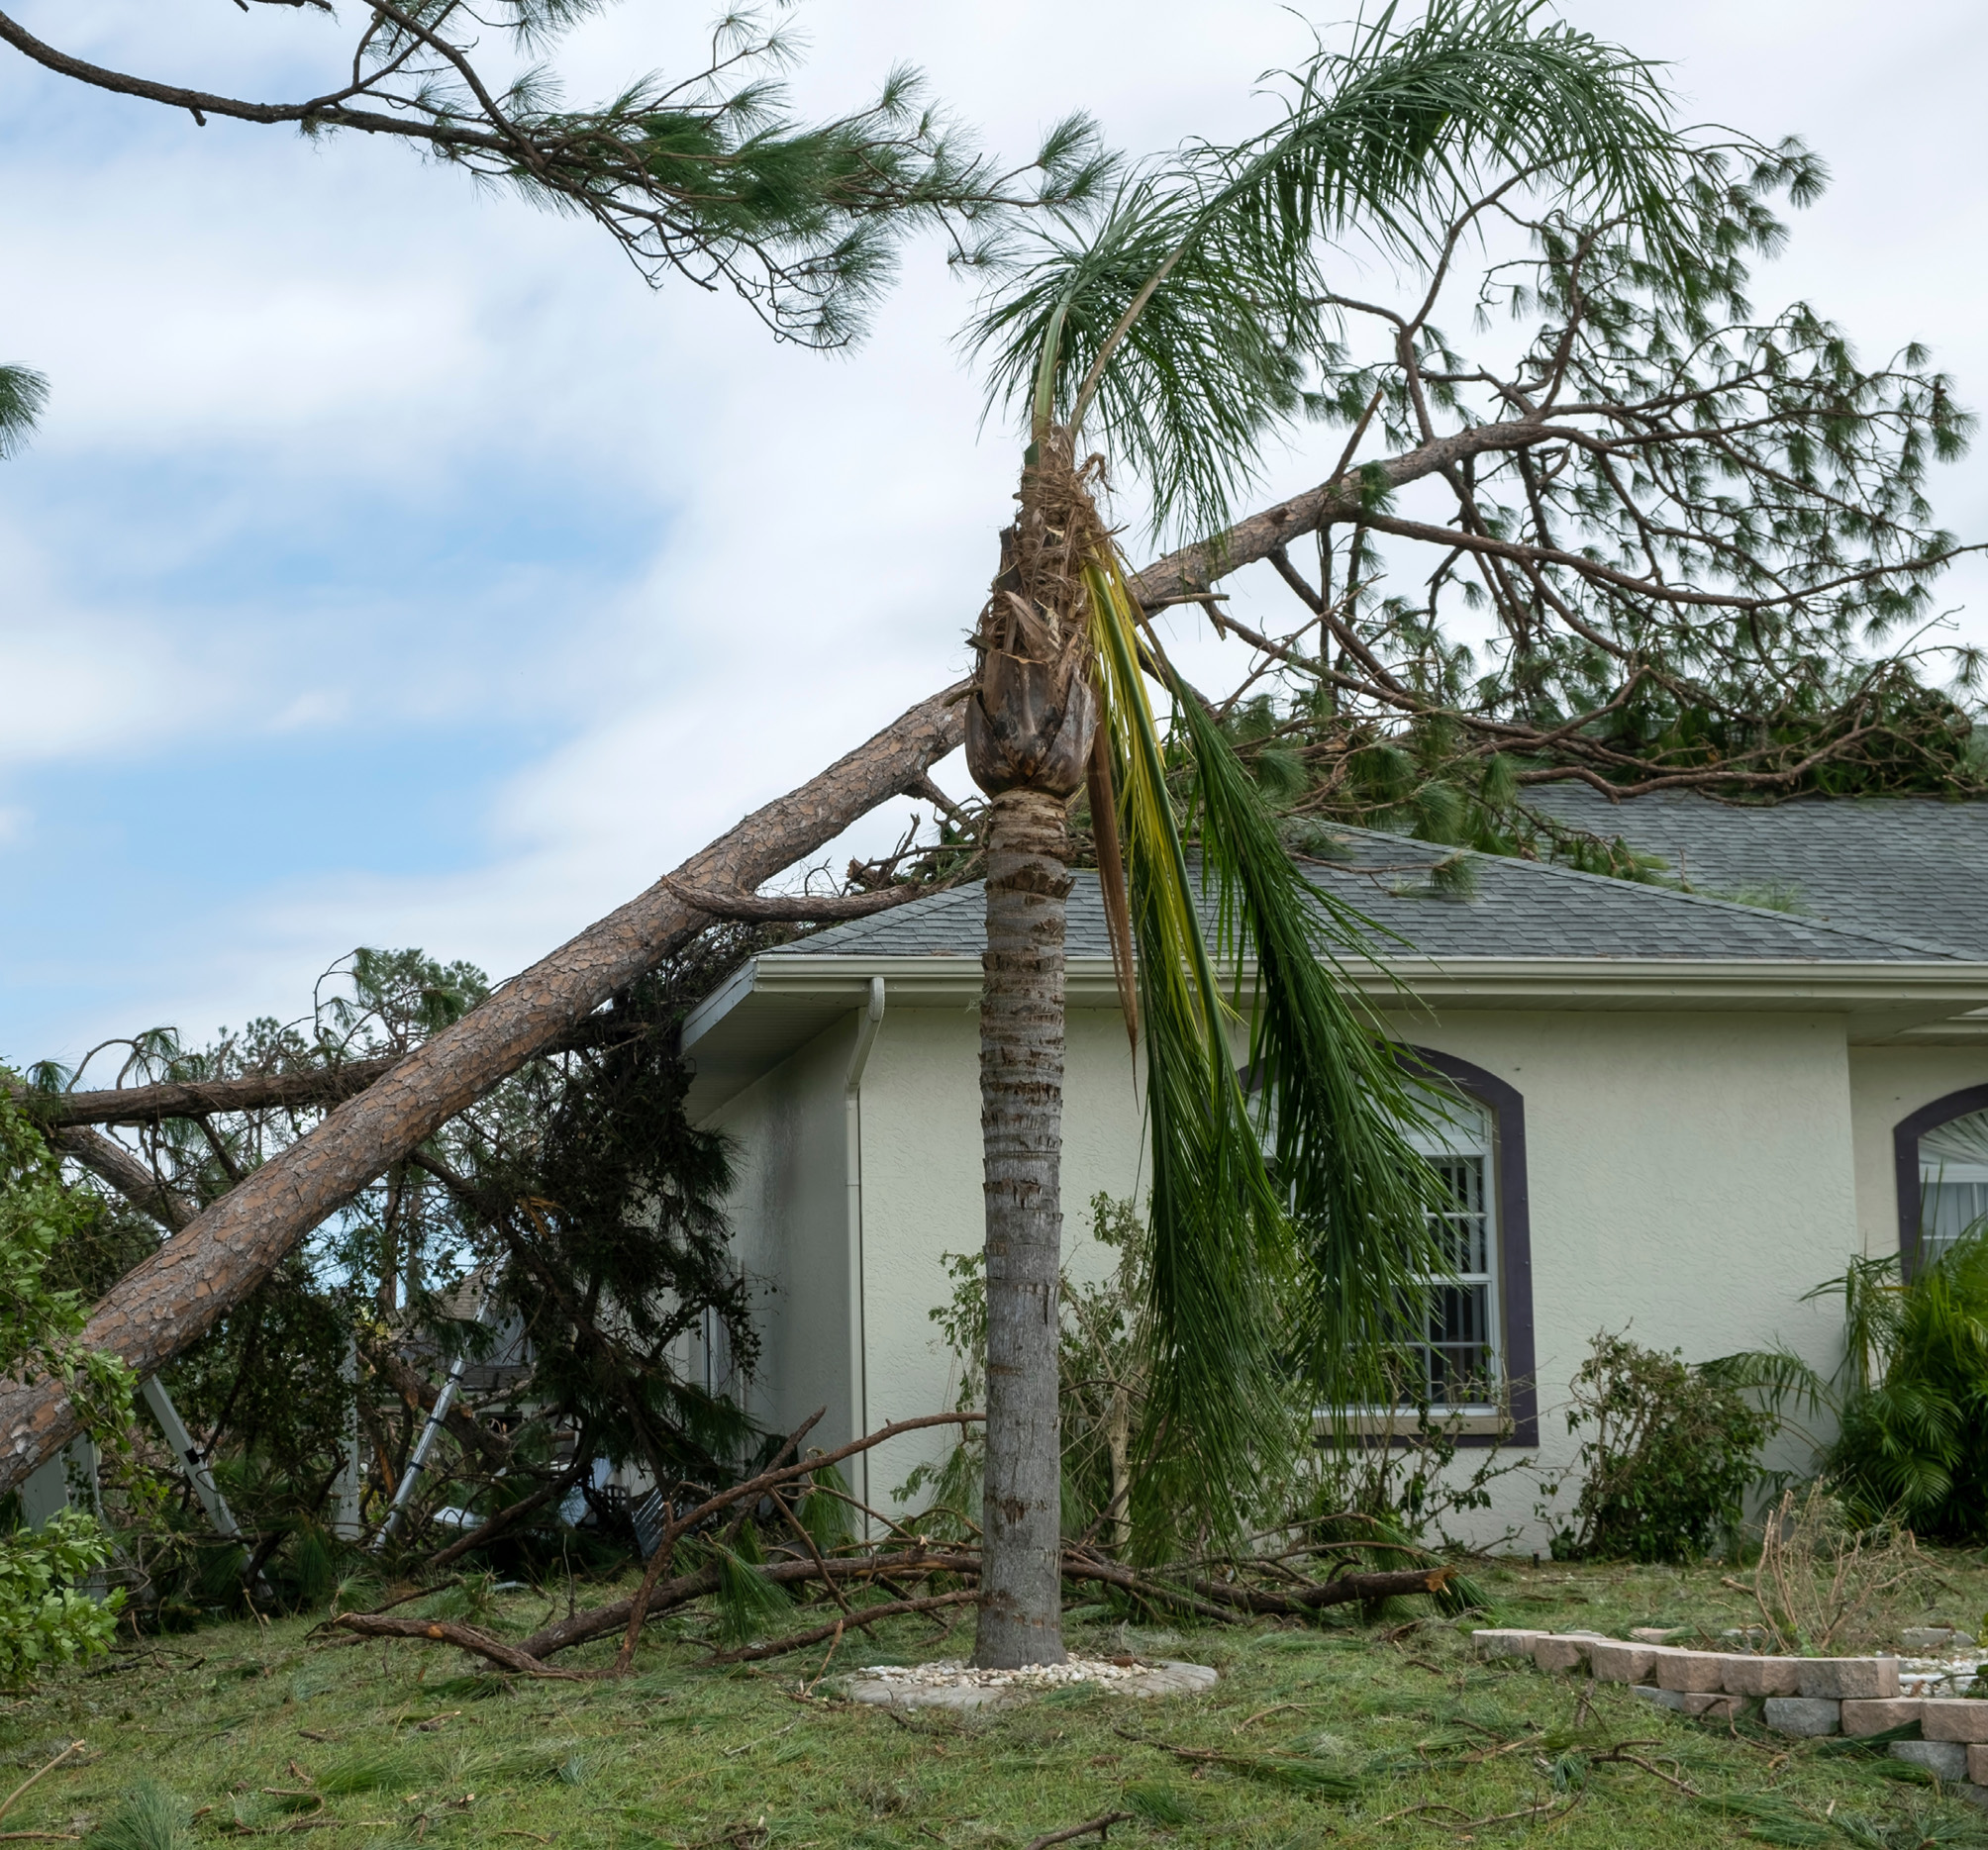
EGA Insights: Role of Adjusters in Navigating Hurricane & Tornado Deployments
Davies’ Specialty Risk Division Executive General Adjusters are elite among Large Loss claims…
-
June 4th 2026
Meet Our EGAs: J. Abraham Hanze—Coast-to-Coast Complex Claims & Specialty Risk Adjuster
Davies’ Executive General Adjusters are elite among Large Loss & Specialty claims adjusters in the…
-
August 6th 2026
Meet Our EGAs: Mike Klein—Mid-Atlantic Adjuster, Umpire & Roof Regulator
Davies’ Executive General Adjusters are elite among Large Loss & Specialty claims adjusters in the…